Terra Balcanica $TERA holds a 39.5% stake in Terra North Resources Corp., its uranium spin-out, which is scheduled to list in Q4 2026.
In short: at a C$2.34M market cap, $TERA's stake in Terra North alone is worth C$1.5M at the last financing price. That leaves the Bosnia silver-antimony project, the company's core asset, valued at roughly C$840k, or $0.0107 per share.
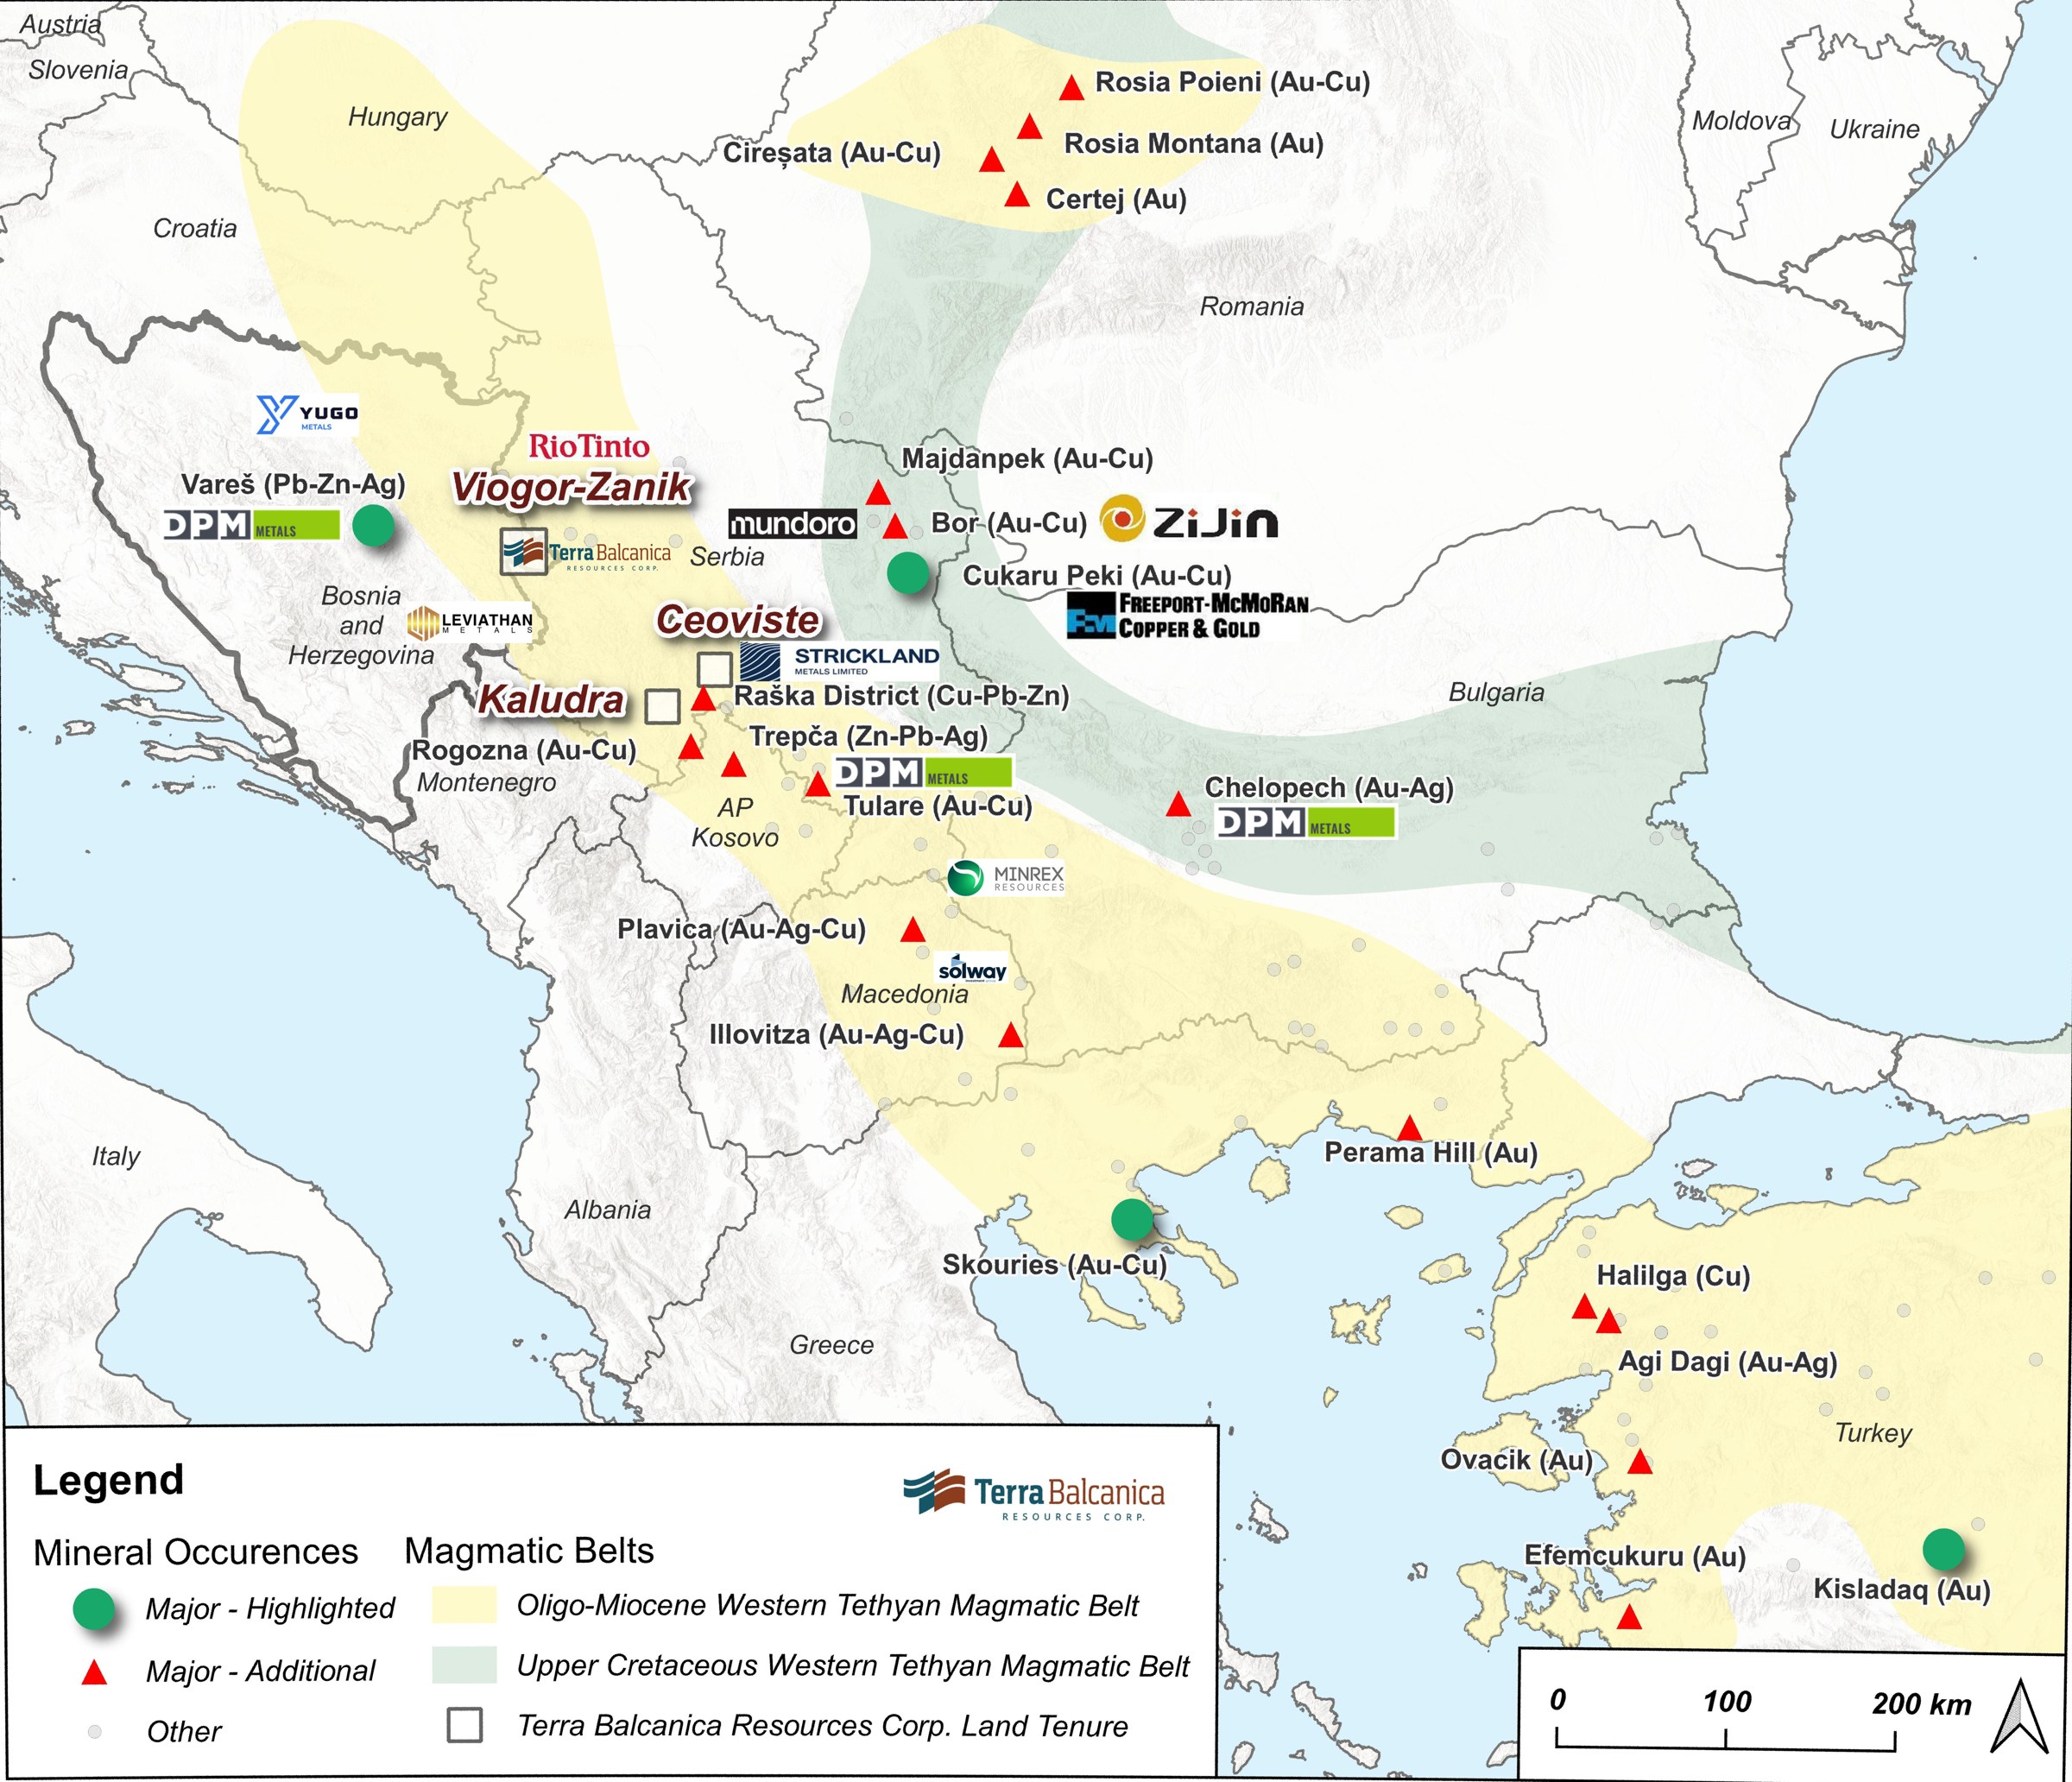
Terra Balcanica's Viogor-Zanik and Čeoviste on the Western Tethyan belt, with DPM Metals' Vareš, Rio Tinto, Zijin and Freeport-McMoRan in the same neighbourhood. Source: Terra Balcanica 3D viewer (GeoIntercept).
Key figures
Price C$0.030 (October 9 close). 52-week range C$0.03 to C$0.18.
Shares outstanding 77.9M (CSE). Reserved for issuance 37.3M, so about 115M fully diluted.
Market cap C$2.34M.
$TERA owns 15M Terra North shares, 39.5% of the company.
Last outside money into Terra North: C$0.10 a share, August 2026, when Fulcrum subscribed for 5.6M shares.
The uranium spin-out
Terra North holds 594 km² of claims near the Athabasca Basin in Saskatchewan. The airborne survey is flown and paid for, and the first results are public. From the company's own release:
"A 16-detector focused gamma ray spectrometer system operated by Special Projects Inc. has now detected 7 prominent (U, Th) radiometric anomalies."
"Preliminary (unfiltered) radiometric data from the 1,000 m spaced, N-S tie lines yielded seven very strong and one exceptionally strong anomaly."
Ask yourself what a reasonable market cap looks like for a uranium explorer with that profile. I did. I am deliberately not posting the answers I got, because out of context they would read as promotion. The point is simpler: the number is not small, and it is worth checking for yourself.
Why Terra Balcanica, and why now
I did not find Terra Balcanica at the bottom. I have held it from considerably higher prices, and I considered it cheap well before the current level. The market has disagreed so far, and that is worth stating plainly. What has changed on the way down is not the assets but the arithmetic: at C$0.030 (October 9 close) and 77.9 million shares outstanding, the entire company is now capitalized at C$2.34M, and the gap between that figure and the sum of the parts is the reason for this post.
Set aside any view on the Bosnia project for a moment. The question I keep coming back to is this: at what $TERA share price does it become attractive to own Terra Balcanica purely as a vehicle for exposure to Terra North?
The math
I think the market is overlooking what the last outside money implies. Fulcrum paid C$0.10 a share for 5.6 million Terra North shares in August 2026.
At C$0.10 a share, all of Terra North is worth about C$3.8 million. That is 1.6x the market value of the parent company, and the parent still owns a silver-antimony project in Bosnia on top of that.
$TERA's 15 million Terra North shares are worth C$1.5 million at C$0.10. Subtract that from the C$2.34M market cap and the core Bosnia project is left with an implied value of roughly C$840k. The numbers look too good to be true, which is exactly why I would rather you check them than take my word for it.
Exclude Terra North, and the market is pricing the rest of Terra Balcanica at $0.0107 per share.
The Bosnia project, in the CEO's own words
That C$840k, or $0.0107 per share, is the market's current price for the following, in CEO Aleksandar Miskovic's own words:
"What Terra (and I personally) have unearthed in eastern Bosnia:
A high-grade polymetallic (gold+silver+zinc+antimony+lead) silver-dominated project with 2 drill-confirmed targets:
Chumavichi: a drill-confirmed, shallow, 650-700 g/t Ag Eq., epithermal vein-hosted target along a 7.2 km corridor.
Brezani: a drill-confirmed, 80 m thick surface gold skarn (0.6 g/t Au; non-43-101 resource of ca. 500,000 oz Au) upon a 20 m wide epithermal antimony-silver rich, fault-hosted mineralization with 436 g/t Ag Eq.
Average antimony grade at both targets: 1-4.5%.
The only European antimony exploration play now that Military Metals’ license in Slovakia has been revoked.
The project is located 80 km east of Adriatic Metals, which was sold to Dundee Precious ($DPM) for $1.33B USD last September with an identical metallurgical mix.
The project is located 960 km from the BMW factory in Munich and the central European/German markets craving secure supply chains of Sb, Zn, and Ag.
A strategic location 8 km from an active mine producing 330,000 t of Ag-Pb-Zn concentrate yearly with crushing and flotation circuits (ore could eventually be trucked to the existing mine, hence there would be no need to spend on CapEx)."
(Aleksandar Miskovic, CEO of Terra Balcanica, posted on CEO.ca, September 5, 2026)
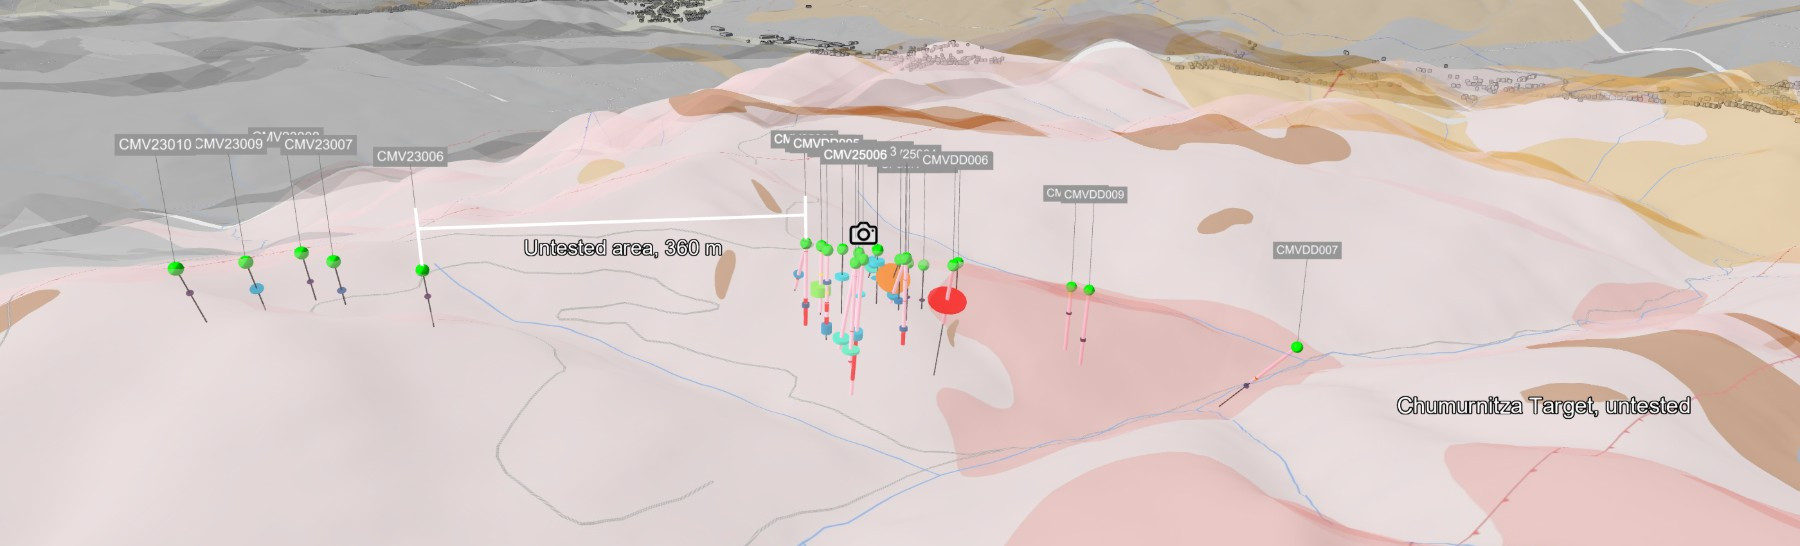
Cumavici Ridge: drill holes with silver assay discs, the 360 m untested gap along strike and the untested Chumurnitza target. Source: Terra Balcanica 3D viewer (GeoIntercept).
The reference point 80 km away is not standing still either. From DPM Metals' third-quarter production release, dated October 8, 2026:
"Vareš produced approximately 45,000 GEO in the third quarter, in line with the planned ramp-up of the mine to full production and reflecting stronger than expected grades."
"The ramp-up of Vareš continues to progress ahead of our expectations and the mine is now expected to exceed its 2026 production guidance." (David Rae, President and CEO, DPM Metals)
Vareš is the operation DPM bought for US$1.33B when it acquired Adriatic Metals. Thirteen months after that deal closed, the buyer reports better grades than it expected and a mine beating its first-year guidance, 80 km from the targets described above.
A neighbour as a yardstick
If the sum-of-the-parts arithmetic feels abstract, there is a direct comparison next door. Regener8 Resources NL (ASX: R8R) has a binding agreement to acquire 100% of the Srebrenica North project in eastern Bosnia. Its own project page describes Terra Balcanica as a "direct neighbour" and lists Terra Balcanica's drill intercepts, including 824 g/t AgEq over 4 m with 1,634 g/t AgEq over 2 m at Cumavici, as part of the case for its ground.
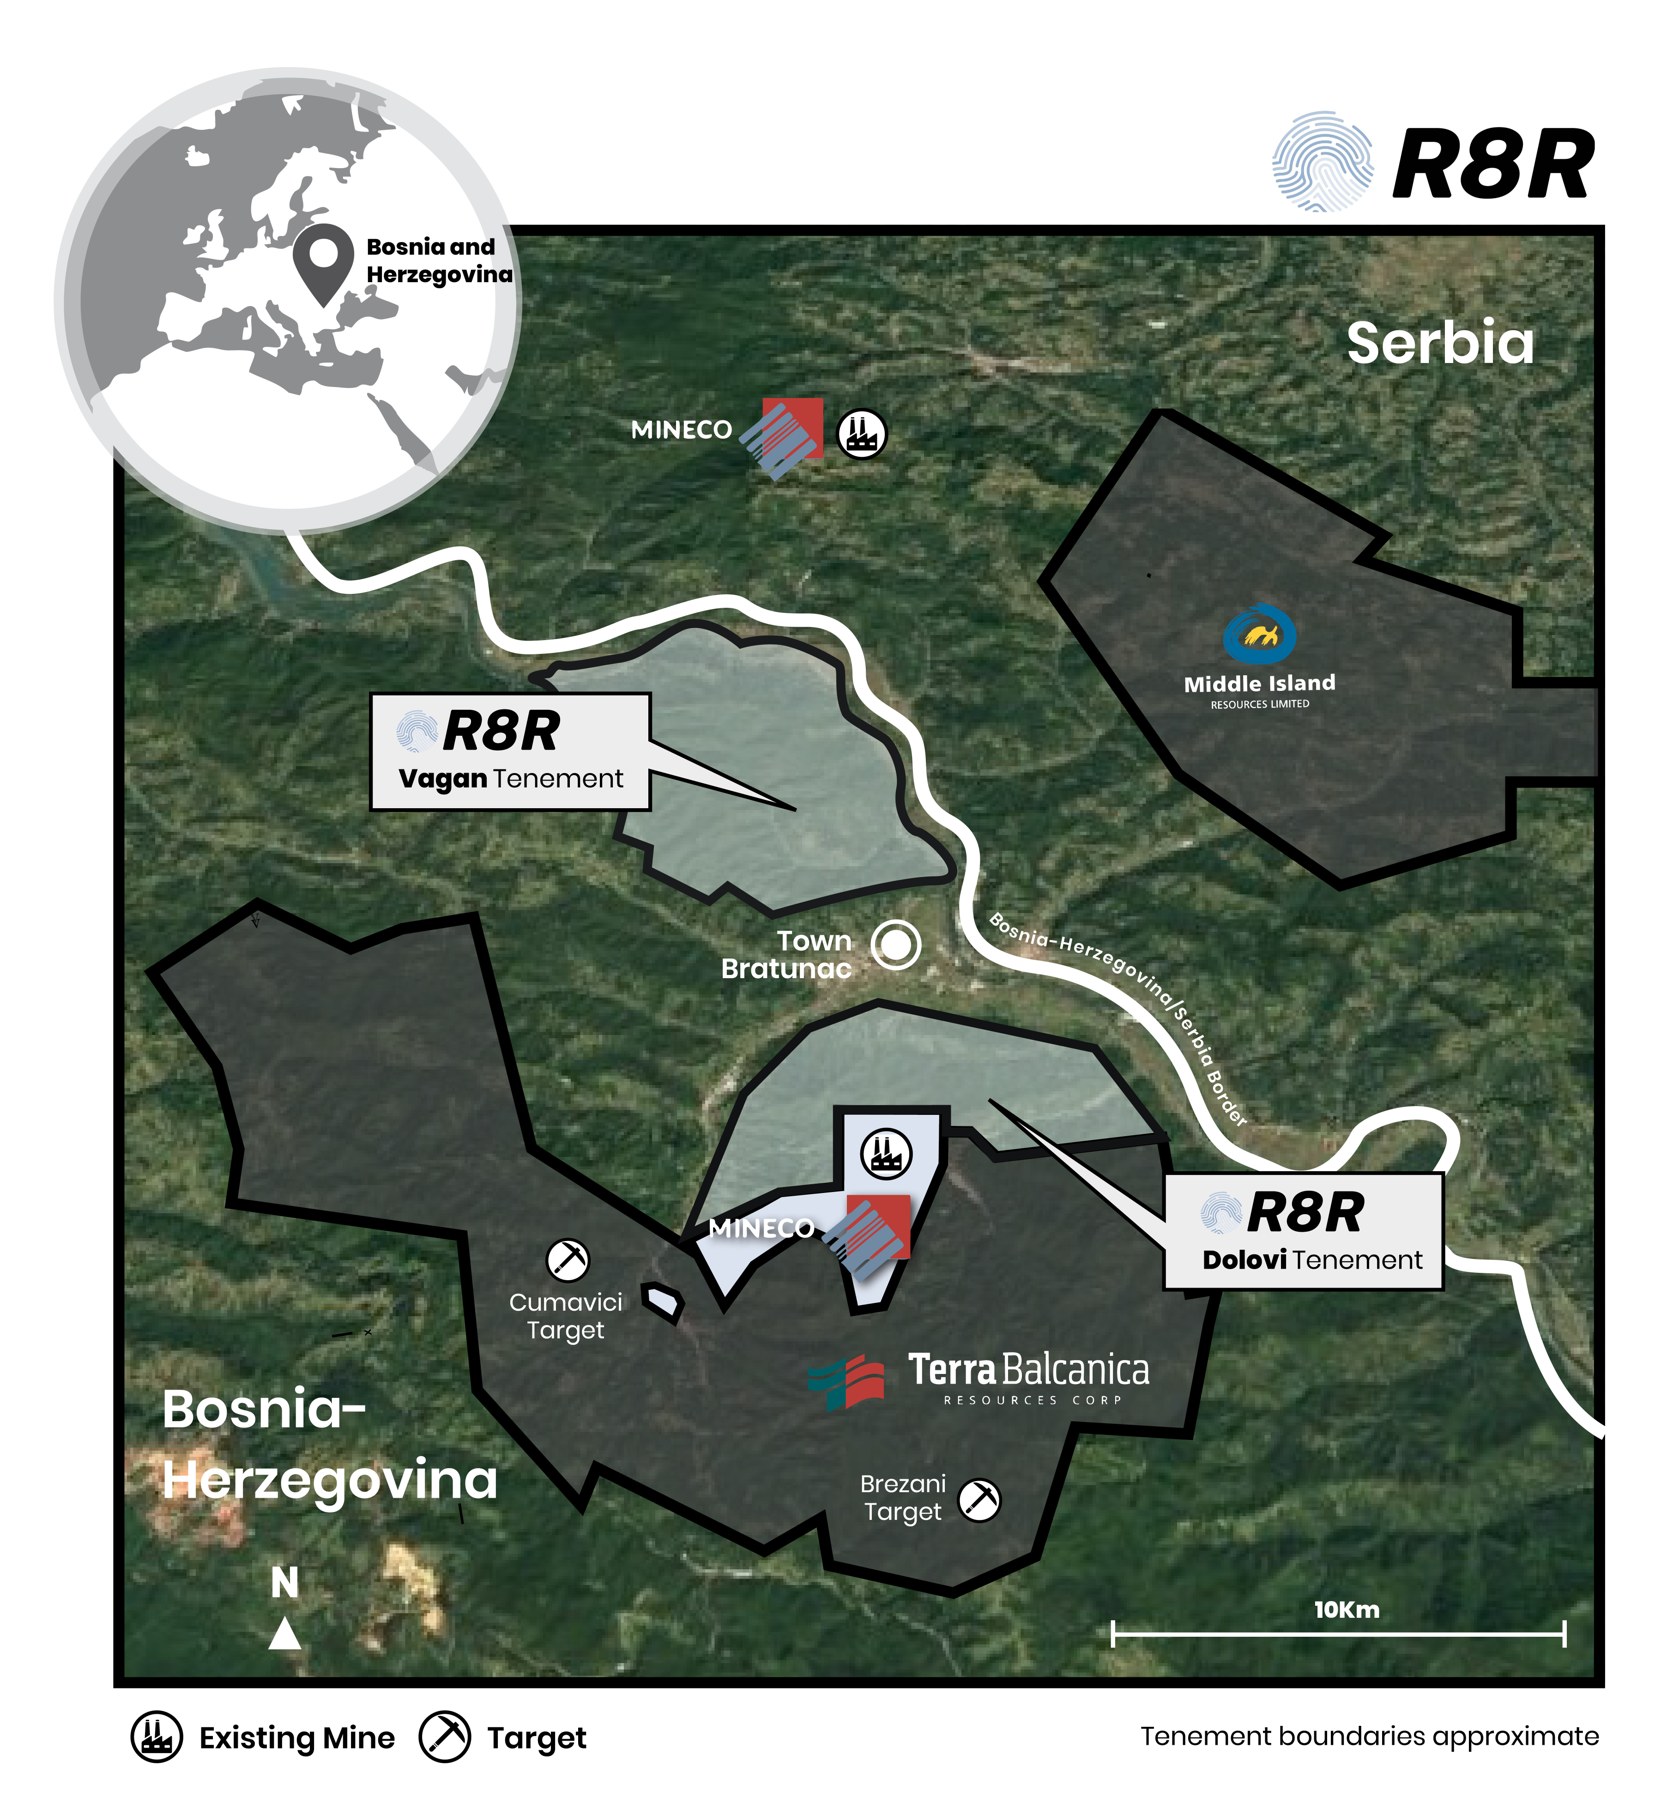
Regener8's own location map. The Dolovi tenement sits in a notch on the northern edge of Terra Balcanica's licence, around Mineco's Sase mine, a few kilometres east of the Cumavici target by the map's own scale bar; the Vagan tenement lies north of Bratunac. Source: regener8resources.com.au, boundaries marked approximate by Regener8.
In the $TERA channel on September 9, @Titanite9 added the other half of the picture: the licence partially overlaps a former Terra Balcanica licence (Chaush) that the company dropped in 2023 because it did not consider it prospective, the current work there is stream sediment and soil sampling, the kind of program Terra Balcanica completed in 2020 and 2021, and no drill targets have been defined yet.
Regener8's market capitalization is about A$9.4M (ASX, October 13), close to C$9.4M at the current exchange rate. That is roughly four times Terra Balcanica's C$2.34M, for an undrilled licence that markets itself with Terra Balcanica's results, and without a 39.5% stake in a uranium spin-out attached.
The comparison gets starker on a like-for-like basis. Regener8 is a Bosnia silver-antimony exploration story and nothing else. The equivalent piece of Terra Balcanica, the drilled Bosnia project after the Terra North stake is stripped out, carries an implied value of about C$840k. C$9.4M against C$840k is roughly eleven times: the market pays eleven times more for the neighbour's undrilled licence than for the drill-confirmed targets that the neighbour quotes in its own marketing.
Both companies can be right about the geology. What is harder to justify is the relative pricing: the company with the drill-confirmed targets and the published results trades at a quarter of the company that references them.
What this comes down to
This post is about one calculation. Terra Balcanica trades at C$2.34M. Its 39.5% of Terra North is worth C$1.5M at the price the last outside investor paid two months ago. The difference, about C$840k or $0.0107 per share, is what the market currently assigns to a drill-confirmed silver-antimony project in Bosnia, 80 km from a deposit that sold for US$1.33B, in what its CEO describes as the only European antimony exploration play.
Nothing about the assets has changed on the way down. The two drill-confirmed targets in Bosnia, the 39.5% stake in a uranium spin-out with a listing targeted for Q4 2026, and the Adriatic sale 80 km away are all in place today. So is the yardstick next door: a company with no drill holes, on ground that partially overlaps a licence Terra Balcanica itself walked away from in 2023 because it did not consider it prospective, promoting that ground with Terra Balcanica's intercepts, and valued by the market at four times Terra Balcanica and eleven times the Bosnia project it quotes.
$TERA #uranium #antimony $silver $gold #zinc #lead #Bosnia #Europe #CriticalMinerals #Athabasca
